Private equity has a cash problem. Buyout funds are sitting on portfolio companies they can't easily sell, in a market where exits have slowed to a crawl, and investors who put money in years ago are still waiting to get it back. So dealmakers have started looking somewhere unexpected for relief: the balance sheets of insurance companies.
The mechanism is a form of structured debt that splits a pool of assets into slices, or "tranches," each with a different level of risk and a different price - the diagram below shows the basic shape of it.
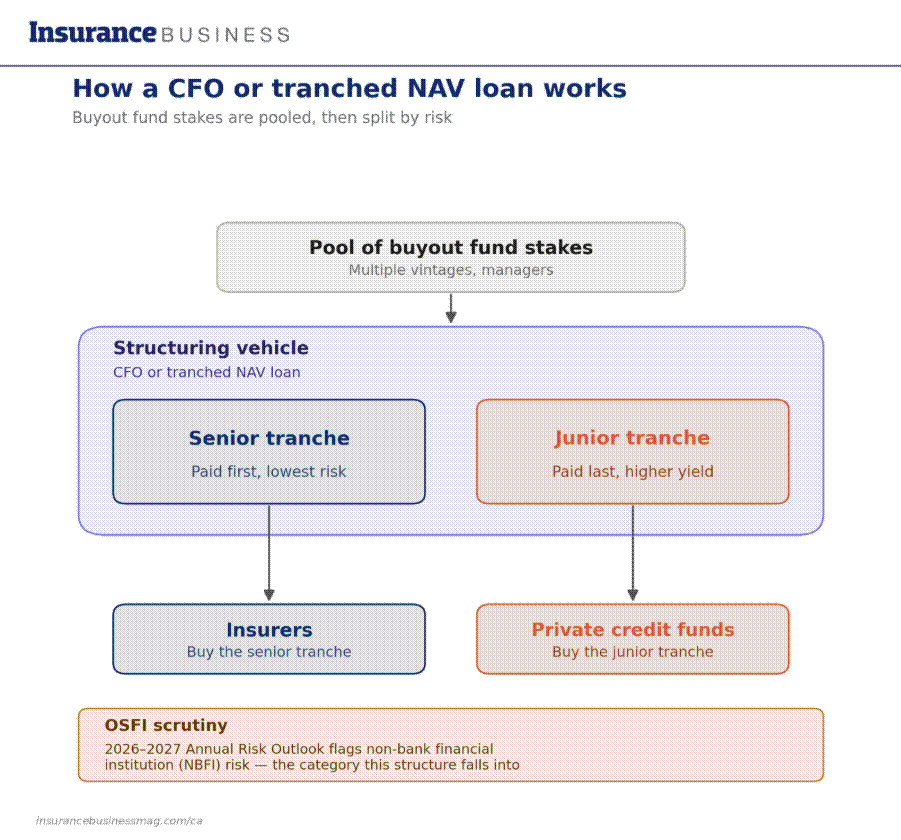
It's the same idea that underpinned mortgage-backed securities before the 2008 financial crisis (remember how that went?), though the assets involved here are stakes in aging buyout funds rather than home loans. The top slice gets paid first and carries the lowest risk; the bottom slice absorbs losses first but pays a higher return. That structure lets an insurer buy only the safest portion, while a hedge fund or private credit firm takes the riskier end for a bigger payout.
Read next: Private credit moves from niche to necessity in Canadian insurers' portfolios
Two structures are driving the trend. The first, collateralized fund obligations (CFOs), package up stakes in buyout funds and issue bonds against them. That’s a technique that has existed for two decades but has recently found a much bigger audience.
Between 2018 and 2024, ratings agency KBRA rated 152 tranches across 67 of these deals, worth a combined US$37.7 billion, according to KBRA's published research. Issuance has kept accelerating since: KBRA-rated CFO volume hit a record US$16 billion by September 2025 alone, on pace to outstrip the prior seven years combined within a single year — the chart below shows the scale of that jump.
The second structure is newer. So-called net asset value (NAV) loans let a fund borrow against the value of its own holdings rather than sell them outright — useful for returning cash to investors or funding fresh purchases without a full exit. Fund managers have now started tranching these loans too, carving them into senior portions rated highly enough to appeal to insurers and junior portions aimed at private credit firms with a bigger appetite for risk. According to Thomas Speller, co-head of funds ratings at Kroll Bond Rating Agency, structuring like this has picked up noticeably over the past year as issuers try to reach "investors with different risk tolerances," a shift he described to the Financial Times.
The scale of the money involved isn't small potatoes. Two of the biggest names in the secondaries business where funds buy up existing stakes in other private equity vehicles have recently gone to market with CFOs of their own.
Blackstone was reported in June 2026 to be exploring the sale of more than US$2 billion in fund stakes through its Strategic Partners unit, with the securities aimed partly at insurance buyers, according to the Financial Times and other outlets at the time. In August, Franklin Templeton closed its first CFO which was a US$1.5 billion deal combining secondaries exposure from its Lexington Partners arm with US middle-market loans from Benefit Street Partners. The firm's own statement naming insurance companies among the target investors, alongside pension funds and family offices.
Read next: OSFI sets out targeted supervisory plans for insurers in 2026-2027 Annual Risk Outlook
Private credit has moved, in the words of OSFI's own executive director for risk assessment, Jacqueline Friedland, from a niche allocation to something insurers here are leaning on more heavily every year.
"The use of private credit has been growing here in Canada," she told Insurance Business, citing global private-credit investment of US$2.1 trillion with annual growth rates near 20% across North America.
That's the same pool of capital, broadly speaking, that CFOs and tranched NAV loans are designed to tap, a federally regulated Canadian life insurer buying a senior CFO tranche is participating in exactly the kind of allocation OSFI has been tracking.
Canada's regulator has also just flagged the structural category these products fall into as a priority. OSFI's 2026-2027 Annual Risk Outlook, published in April 2026, names non-bank financial institution (NBFI) risk. That’s exposure to lenders and investment vehicles outside the traditional banking system, which is exactly what a secondaries fund or a CFO issuer is as one of three top risks facing the Canadian financial system this year, alongside real estate lending and funding risk.
Separately, law firm Torys LLP has argued publicly that OSFI should move to a "look-through" capital treatment for life insurer investments in private credit funds under the Life Insurance Capital Adequacy Test (LICAT), calculating capital requirements on the underlying assets' actual risk rather than treating the investment more bluntly. That’s a change that, if adopted, would apply directly to how a Canadian insurer's CFO tranche gets capitalized.
Read next: Private equity is starting to control Canada's insurance brokerage sector
Layering debt on top of buyout funds that are often already leveraged at the portfolio-company level adds to that concern, since losses can stack up in ways that are harder to see from the outside.
A handful of secondaries managers reportedly began tranching their own NAV loans to reach insurers only this year, according to a private credit executive who spoke to the FT meaning underwriters and capital teams are being asked to get comfortable with a fairly untested corner of structured finance rather quickly, right as OSFI itself is signalling it wants closer visibility into exactly this kind of exposure.
There's also a banking angle worth watching. Some lenders have reportedly been selling off the riskiest slices of the NAV loans they extend to private credit funds as a way of freeing up their own capital - with buyers including private credit shops themselves.
That's a pattern insurers evaluating these deals may want to understand before assuming a senior tranche is as insulated as its rating implies.
Read next: Budget 2025 and insurers: Capital threshold changes and expanded OSFI powers
None of this is likely to slow the trend. Private equity firms need liquidity, and insurers everywhere are sitting on long-term capital that has to go somewhere. What's changed is the sophistication of the products being built to connect the two — and the speed with which they're moving from niche financing tool to mainstream fixture of the secondaries market, right as OSFI builds out the supervisory framework meant to keep pace with them.