Canadian small business owners are confident about finances they can't actually back up, a gap that leaves many one bad month away from a crisis they didn't see coming, and a clear opening for brokers who can spot it before the client does.
A TD Insurance survey published this week found 23% of small business owners carry no business insurance at all despite 90% reporting an unexpected setback in the past year, while a separate national benchmark, the Zenbooks Financial Clarity Index, a survey of 565 Canadian SMEs weighted to Statistics Canada figures for region, employee size, and sector, found the same overconfidence runs through financial management more broadly. The national score on that index came in at 56.7 out of 100.
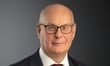
More than a third of owners, 35.2%, rate their own finances as good or excellent while actually scoring below 60 out of 100 on the index. "That means roughly one in three Canadian business owners are confident about something that they actually can't demonstrate," said Eric Saumure (pictured), CPA and principal at Zenbooks.
Read more: TD's third annual survey finds the same small business insurance gap again
The same gap shows up on more specific measures. About half of owners surveyed said they could confidently rank their own product's profitability, but only four in ten actually track it at all.
That overconfidence is sharpest among businesses with the weakest financial infrastructure. Firms running on mostly manual processes overestimate their own financial understanding by 21.3 points on average, compared with just 5.0 points among firms operating on fully integrated financial systems.
Saumure has his own theory for why the gap exists. He said business owners typically lack the kind of feedback loop an employee gets from a manager, and that the professionals owners do consult, including their own accountants, tend to agree with them rather than challenge their self-assessment. "It doesn't support that feedback loop," he told Insurance Business.
Two other findings ran counter to Zenbooks' own commercial interest, Saumure joked, which is part of why he trusts them. The index found no association between outsourcing a company's finance function and greater financial clarity, despite Zenbooks running an outsourced accounting practice itself. It also found no relationship between how often a business owner talks to their accountant and their risk of being audited.
The gap extends to basic questions of business fundamentals. Nearly a quarter of owners, 23.3%, don't know what their business is actually worth, a blind spot Saumure said carries real consequences in shareholder disputes, family law matters, and retirement planning. "It's a pretty difficult thing for people to grasp," he said, "because they're often not in the finance industry or they don't understand valuations."
And 24.9% of owners hold neither an emergency fund nor a line of credit, leaving them with limited ability to absorb a financial shock. Saumure said that gap pushes owners toward faster, shorter-term decisions rather than longer-term investments that tend to serve the business better. By contrast, owners who hold both an emergency fund and a credit line scored notably higher on the index's measure of financial understanding.
Company size explained more of the variation than any other factor, Saumure said, to the point that Zenbooks had to control for it directly in its analysis. "Generally speaking, larger businesses understand their finances way, way better," he said. "They have more reserves and they're just better organized."
One further finding stood out to Saumure on its own: 27.6% of owners reported delaying their own pay in the last 90 days, often without telling their staff or even their spouse. "They're the shock absorbers in this economy," he said. "They pay their vendors, they pay the CRA even before they pay themselves, and nobody around them often even knows."
That disconnect between belief and reality carries directly into how owners handle insurance itself. A TD Insurance survey conducted by Leger Opinion among 401 Canadian small business owners found 76% agreed coverage should be a core part of business planning, yet 23% remained uninsured and 24% still treated it as a cost to minimize rather than a planning tool. More than half, 55%, said they couldn't cover an unexpected expense over $10,000 without outside help, a thin margin that echoes Zenbooks' own finding that nearly a quarter of owners hold neither an emergency fund nor a line of credit.
"While it's encouraging that most business owners report having business insurance, our findings suggest there is still a gap in understanding how coverage can help support and protect their business as it grows," said Tang Trang, TD Insurance's vice president of small business insurance.
Read more: Why brokers should worry more about the risks their SME clients aren't worried about
Brokers are already seeing the same pattern firsthand, according to Mariano Neiman, COO at Zensurance, who has told Insurance Business that the single biggest misconception small business owners carry about insurance isn't about price at all, it's the belief that "it won't happen to me." Zensurance's own survey found two-thirds of small business owners carry no insurance whatsoever, and when asked why, cost trailed well behind more fundamental reasons: 38% said they didn't think they faced the kind of risk insurance covers, and 29% said they didn't think they needed it at all.
Neiman's data points to a similar fragility on the financial side. Zensurance found 81% of small business owners are sitting on three months of cash reserves or less, with four in ten holding less than a month's worth. That thin runway changes the math on what counts as a serious incident in the first place: a retail theft resulting in $5,000 of stolen inventory and a few thousand more in property damage can be enough to shut a business down for two to four weeks, Neiman said, simply because there's no cushion to absorb it.
That fragility often extends beyond the business itself. Neiman said 39% of business owners are financing their business with a personal credit card or home equity, blurring the line between a business setback and a personal financial one. Non-payment for completed work ranked as the single biggest concern among owners surveyed, at 29%, ahead of cyberattacks at 14% and theft or vandalism at 9%, even though Neiman said the bigger existential threat, a large liability claim or lawsuit, tends to rank far lower simply because fewer owners have experienced one firsthand.