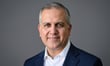
Adam Okun (pictured) started out as a numbers guy with a job to do and no particular agenda. By the time he had spent three years running actuarial analysis for Fortune 500 companies, he had developed one.
After graduating in 2006, he followed a path into actuarial science that parents and mentors had recommended, recognizing his talent for mathematics. As he worked with employers of all sizes, however, a clear disparity emerged. Large corporations had access to tailored advice and deep strategic support, while many mid-sized businesses were left with standardized solutions and limited guidance. “What became very evident to me in a short time was that middle-market organizations that didn’t have the resources and capital that the large Fortune 500 companies did were terribly underserved,” he said. “By employee benefits consultants.”
In 2009 he pivoted, joining a regional brokerage firm focused on exactly that segment. He differentiated himself quickly by building financial narratives and bringing sophisticated counsel that middle-market clients had simply never encountered from a benefits advisor before. The firm was acquired by EPIC Insurance Brokers & Consultants in 2017, and Okun has taken on successive leadership roles since, culminating in his current position as president of EPIC’s Employee Benefits Organization, one of the largest independent brokerages in the country.
Sitting in that seat today, Okun sees the industry in a period of transformation he has no hesitation calling unprecedented. There are four forces at work simultaneously.
The first is technology and artificial intelligence, which he says has opened up possibilities in employee engagement, communication, benefits administration, and analytics that simply did not exist even a year ago.
The second is the explosion of new product structures, individual coverage health reimbursement arrangements (ICHRAs), captives, and direct-to-consumer products, pulling employers away from the traditional large carrier model.
The third is regulatory pressure bringing transparency to pharmacy benefit managers (PBMs), giving employers and their consultants tools to interrogate drug pricing that they have never had before.
The fourth is the consolidation and merger-and-acquisition activity sweeping through the middle market, driven not just by private equity but by family offices, sovereign wealth funds, and trusts.
That last one has changed the game for brokers in ways that are still playing out. New capital allocators do not come with long institutional memories and a fondness for the existing broker relationship. They come with procurement teams, governance frameworks, and a mandate to scrutinize spend. “There’s no longer the luxury of just resting on your laurels or relying upon a social relationship to ensure that you are going to be protected as a broker for a decade plus,” Okun said. The consultants who want to keep their clients need to resell their value every single year.
So what does genuine strategic consulting look like in practice? Okun breaks it into three layers.
The first is understanding the client’s governing philosophy, their objectives, how robust a benefits program they want to offer, what trade-offs they are willing to make between coverage and cost, and how they want to position themselves in the competition for talent.
The second is a capital allocation conversation: does this employer want to be fully insured, take on some level of risk, or move further toward self-funding? How much reinsurance protection makes sense given their risk tolerance?
The third layer is where the creativity comes in. Increasingly, employers are unbundling their purchasing decisions, selecting specific vendors for behavioral health, disease management, weight management, and a growing list of point solutions, rather than accepting whatever a large carrier puts in front of them. “You have to become familiar, you have to be adept as a consultant at the entire breadth of point solutions and products in the market,” Okun said, “to ensure that you’re not just buying an off-the-shelf solution that is entirely pre-formatted by a large national carrier, but instead is totally bespoke based upon the unique conditions of that client and its membership.”
Of every issue he raised, Okun returned most urgently to pharmacy. Historically, drug spending represented less than 10 percent of total employer healthcare budgets. For 2027 renewals, he says it is approaching 35 percent for his middle-market clients, citing RX data.
The profits are not being made on the medical side. They are embedded in the pharmacy purchasing decision, through spread pricing, rebates, and what Okun calls “non-transparent and obscure profit levers” built into PBM contracts. He points to two data points that make the scale of the problem clear. “There’s a reason why CVS purchased Aetna,” he said. “There’s a reason why the majority of the earnings on UnitedHealth Group’s calls are driven by Optum, not by UnitedHealthcare. Pharmacy is where the profits overwhelmingly lie.”
EPIC’s response was to integrate PSG (Pharmaceutical Strategies Group), formerly described as the largest independent pharmacy consulting practice in the country, historically serving health plans, large insurers, and Fortune 100 companies into its middle-market consulting platform. A well-managed pharmacy consulting relationship, according to Okun, can produce approximately a 30 percent reduction in pharmacy spend. At 35 percent of total costs, that translates to roughly a 10 percent reduction in total healthcare budgets. Without that expertise, the math is uncomfortable. “Any major middle-market employer that doesn’t have an expert pharmacy consultant aligned to the relationship is almost certainly hemorrhaging five to 10 percent at a minimum out of their total healthcare spend,” he said.
His advice to brokers on what to ask a PBM is direct. Start with the contract. Read the specific terms and pay close attention to how average wholesale price (AWP) is defined and what qualifies as single-source generics. Seemingly minor details can have significant financial consequences. Then pull the group-specific utilization data, which drugs members are using, which pharmacies they are using, and what the pricing arrangements are for specialty drugs. With both the contract language and the claims data in hand, a pharmacy consultant can assess whether the program is structured in the client’s interest or the PBM’s.
Beyond pharmacy, Okun points to several approaches delivering real results for middle-market employers right now. Self-funded and level-funded products are increasingly accessible to smaller employers, and gaining visibility into claims data is the essential first step for everything else. Engineered networks, directing members toward providers who score highest on quality and efficiency, through incentive design or narrower network structures are proving effective for employers prepared to make that move.
Clinical edits within pharmacy programs are also moving the needle. These require members to complete specific steps before accessing a preferred drug and actively message clinicians with alternatives based on member utilization data. Then there are the broader structural options: third-party administrators with aggressive claims governance, ICHRAs as a fixed-subsidy alternative particularly for smaller employers, and captives that allow groups of employers to band together and gain collective scale in pharmacy and reinsurance purchasing.
“The spectrum of options is very robust,” Okun said, “more robust and creative than I’ve ever seen at any point in my career.”
On artificial intelligence, Okun is energized rather than anxious. His argument is straightforward: AI will commoditize the administrative and analytic layer of brokerage delivery, communications, monthly financial reporting, member-facing administrative platforms that brokers have historically leaned on to stand out from competitors. Once that layer is commoditized, differentiation moves upward to strategic consulting, plan design, product unbundling, and the governance of a more thoughtfully constructed insurance purchase.
For a firm like EPIC, which has invested in technically specialized consultants with deep expertise across industries and client segments, he sees this as a significant opportunity rather than a threat. “The opportunity set for those who are enthusiastic and ambitious and curious and willing to learn about what’s possible in this new world order is massive,” he said.
The three-to-five-year picture he paints is one of clear bifurcation. The best consultants will use technology to serve larger client bases, find underserved employers across the country, and build reputations on genuine strategic value. Relationships built on inertia, he suggests, will not survive that scrutiny. “I’ve never been more excited about the opportunity that forward-thinking consultants have in front of them than I am today.”
Ask Okun what he does when the working day ends and he laughs. “That’s the hardest question you’ve asked today,” he said. The demands of the role make fully disconnecting genuinely difficult. But outside the office, his life is full. He has five children who keep him well occupied, travels frequently with his wife and family, and works out a couple of times a week.
When the pace does slow, he turns not to a screen but to religious study. He works through Talmud regularly and gives a weekly scripture class. It is, on reflection, a fitting way for someone in his profession to find balance. The Talmud, like a PBM contract, rewards those willing to sit with complexity, resist the easy reading, and look past the surface for what is actually written there. In an industry built on fine print that most people never examine, Adam Okun has always been the one who does.