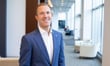
Mathew Rehbein (pictured) spent 17 years inside corporate insurance. Claims, underwriting, two years on a catastrophe response team deploying to hurricanes and tornadoes across the country. Then in 2017 he walked out the door and made himself one promise: never again. Today he is a benefits broker of a different kind. One who goes to the job site, never buys a lead, and built an entire cross-selling practice around one simple rule: listen more than you talk.
Rehbein, founder and CEO of Rehbein Consulting and Legacy Ignited in Connecticut, has 26 years of industry experience and works primarily with small to mid-size employers across New England. He calls his approach old school. And he means it.
"When I walk into a business, I want to learn about what makes up that business," he said. "Know the business owners, know their family, get to know the employees, know their families also. So if the business isn't doing something for their employees, how can I get some benefits or something in there that they can offer, which also can be a tax write-off for the business?"
That big-picture approach is what keeps his pipeline full without purchasing a single lead. According to him, it is also one of the most overlooked skills in the profession, with many producers too focused on today's business to invest in tomorrow's.
Most firms keep commercial insurance and employee benefits in separate silos. Businesses do not. Rehbein has spent years exploiting exactly that gap, walking into a general liability conversation and walking out with a group health or voluntary benefits relationship alongside it.
His richest recent territory has been low-income and habitational housing, a fast-growing segment across New England and the New York boroughs that most producers have overlooked. He is placing business in Brooklyn, Queens, and western Massachusetts, working with developers refurbishing older buildings as well as those constructing new affordable housing.
"Producers for the last 10 or 15 years haven't really had to deal with that," he said. "They don't know how to. So that's a huge opening right now."
His approach to understanding those businesses goes further than most producers are willing to go. Rather than building a proposal from paperwork alone, Rehbein visits job sites, construction projects, manufacturing floors, habitational properties under renovation, to see the operation firsthand.
"I want to go out to the job site," he said. "I want to see what's going on so I have a better understanding of how the business is being run. Where most other producers, they'll just take the insurance paperwork and work off of that. No, I want to go into the business physically and learn and see, understand how it all works."
The cross-sell comes naturally from a relationship built on coverage depth rather than price alone. When he sits down with a business owner, Rehbein moves through commercial lines, then personal umbrella, then employee benefits, not as a checklist, but as a conversation.
The personal-lines cross-sell is often the simplest opportunity in the room and the one most producers never raise.
"Slip and fall happens," he said. "I've seen it. I've handled those claims." His claims background gives him a credibility most producers cannot replicate, he is not speculating about exposure, he has processed the losses.
Rehbein's claims and underwriting background shapes the way he frames coverage decisions for clients who might be tempted by the lowest-premium option.
"I might be $5,000 more," he said, "but it's better to pay the $5,000 than if you have a loss, it's going to cost you $500,000."
His path to that listening moment is itself methodical. Rehbein does not cold call. Instead, he sequences every prospecting effort the same way: a LinkedIn connection with the company president, vice president, or head of marketing, then a phone call, then an email, and finally the step he considers non-negotiable, an in-person visit.
"Old school, boots on the ground," he said. "I want a handshake. I want face to face. You're going to get more yeses with a face-to-face than you are over the phone."
Only once he is in the room does the listening begin in earnest.
"I have a brief two-minute introduction conversation with back and forth," he said, "and then I just shut my mouth. I let them go on for a half hour. They'll answer the other eight or nine questions that I had, and I don't even have to ask."
He reviews every client's policies every six to eight months, checking for changes in headcount, fleet, operations, or specialization that could affect their coverage or create a new opportunity. That cadence positions Rehbein as a strategic partner rather than an annual renewal call.
"I don't need leads because the business comes to me," he said. "You take care of them if you listen and do what the client tells and says, and you help them where they're struggling."
As plan sponsors face mounting pressure on group health costs, from premium inflation to labor market volatility, brokers who can surface risk across both commercial and benefits lines are finding themselves in stronger renewal positions.
For Rehbein, the business has never really been about the business. Every client relationship spans multiple layers: the owner, their family, the employees, and their families in turn. He wants to know all of them.
"It's all about multi-layers of lives," he said. "The business owners, their family, the employees, their families. It's more than one thing. You've got to look at it from a different perspective and take the whole picture and create a story around it."
Caring for employees through meaningful benefits is not just the right thing to do, he argues, it is also good business. When a company invests in its people, those people notice. They stay longer, perform better, and make the business stronger.
Part of what that looks like in practice is making sure clients see him as someone they can call between renewals, not just at them. When a client mentions they are thinking of expanding into a new area or taking on different work, he wants a heads-up before they sign anything.
"When I tell them that, they're like, 'Really? I can call you to ask you that?'" he said. "I say, yeah. It's like calling your financial advisor or calling your accountant."
That positioning, available, proactive, invested in outcomes rather than just premiums, is, what he believes separates brokers who build lasting books from those always chasing new clients to replace the ones they lost.
For Rehbein, the real measure of the work is not the commission. It is something harder to put a number on.
For him, the greatest reward is not the sale itself, but the impact behind it. “You’re changing people’s lives and helping families,” he said. “If you’re in it for the right reasons, there’s a real sense of fulfilment in knowing that what you did today genuinely made a difference to someone else.”
He draws a direct line between the way he sees his own family and the way he sees his clients'.
"Don't you want the same for your clients and their family as well?" he said. "It's kind of like, look at yourself in a mirror in a weird way, but see them with their own family. They have to be happy too. We all struggle, we all have ups and downs, but we do it together."
Rehbein describes himself as a convert to artificial intelligence tools. He uses AI primarily for scheduling, sorting clients by industry and coverage type, and automating policy-change logic, tasks he estimates previously consumed two to three hours of his working day.
"I wish this was around 10 or 15 years ago," he said.
For producers chasing volume over relationships, he sees the risk running in the other direction. Efficiency tools accelerate whatever habits are already in place. For a relationship-focused advisor, AI frees time for the face-to-face conversations that build referral networks. For transactional producers, it can widen the gap between them and advisors who invest in depth.
"It's all about the money, the churn, and the burn," he said, describing the pattern he sees in some newer agents. His own philosophy runs entirely the other way: "It's all about caring about the business, the family, the people."
Away from the office, Rehbein is either in the stands or under the hood. His two daughters keep him busy with dancing and lacrosse. Classic cars are his own project: he refurbishes them in his spare time, and his daughters have been part of the crew since they were small enough to slide under the chassis. Both can now change brakes, swap tires, and check the oil. That is not an accident. “Don’t ever have to have a man support you,” he tells them. It is the same instinct, perhaps, that runs through everything he does at work too. Teach people what they need to know, make sure they can stand on their own, and trust that the rest will follow.