Elliot Lake hasn’t changed its insurance broker in seven years. It will be at least one more council meeting before it does.
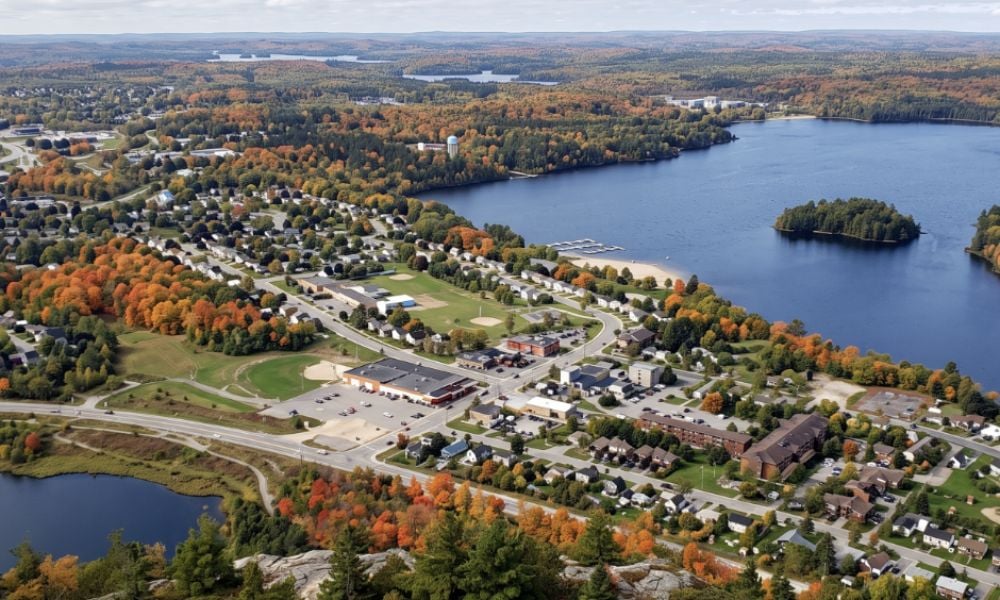
The city, on the North Shore of Lake Huron, ran an open request for proposals for brokerage services this year. Three firms bid: Jones Insurance, BFL Canada and BrokerLink. Staff recommended Jones for a five-year term. Jones was the lowest bidder and agreed to cap its brokerage fee at between $30,000 and $40,000 a year, depending on the year.
Finance director Andrew Ault told council the switch would cut about $70,000 a year from what the city now pays for brokerage, before any insurance quotes have come in. He said more savings could follow once the new broker takes the program to market.
The council, however, wasn’t ready to sign off. The vote was split, and Mayor Andrew Wannan broke the tie in favour of deferring. Wannan said he liked the savings but agreed council needed more detail. Staff will return with a side-by-side comparison of all three bids.
Coun. Norman Mann’s objection was about how the bids were priced. BFL offered a flat fee. The other two bidders quoted percentages of whatever premium the city ends up paying. The city’s insurance bill is already close to $1 million a year, and no new premium figure exists yet. Mann said that made it hard to know what the percentage-based bids would actually cost, and that council should have seen the full insurance cost as part of the process.
Ault’s answer was about sequence. The city has to appoint a broker before it can get insurance quotes, because the broker is the one who goes to market.
Brokers who work in the public sector will know this problem well. A percentage-of-premium bid only becomes a dollar figure once the premium is set, so the buyer is comparing estimates against a fixed number. A cap removes most of that uncertainty, which helps explain why Jones’s bid stood out. On a program close to $1 million, each percentage point of commission is worth nearly $10,000 a year.
Read next: Municipal loss ratios under the microscope in Tillsonburg insurance briefing
Ault credited Jones’s lower price to the commission cap and to the firm’s ownership. “This is not a nationally owned firm,” he told council, and described Jones as locally owned and fully independent, with no outside owner setting its commission levels.
That remark carries weight given the other bidders. BrokerLink is owned by Intact Financial, the country’s largest P&C insurer. BFL Canada is a national brokerage that has been moving deeper into product design and includes municipalities among its clients. For a small northern city, the choice also involves who owns the advice, not only what it costs.
Jones’s proposal also included service commitments:
Ault also explained to council how a municipal insurance program is structured. The insurer holds the capital and pays the claims. The managing general agent puts together programs that spread the risk and is paid by the insurers. The broker represents the municipality. Its job is to make sure legitimate claims aren’t denied, the program is well designed and risks are properly managed.
Elliot Lake’s caution makes sense in context. Insurance is now one of the larger budget items for small Ontario municipalities. The Association of Municipalities of Ontario says many members have seen premium increases of more than 20%. AMO points to a hard market, climate change, rising litigation and Ontario’s joint and several liability rules under the Negligence Act.
Under those rules, a municipality found even slightly at fault can end up paying much more than its share of a damage award. That has pushed councils across the province to rally behind calls for liability reform. It has also contributed to double-digit premium increases in rural townships.
Read next: Small municipalities exposed as dam failure leaves insurance gaps
The timing of the tender may suit the city. Commercial property pricing in Canada was expected to remain stable well into 2026 because of plentiful capacity. A broker going to market now may have more room to negotiate than one would have had a few years ago, although municipal liability is still a difficult class for many underwriters.
Brokers bidding on public-sector work should take note of what Elliot Lake asked for. Price won the staff recommendation, but council wanted transparency about compensation before voting.
Councils are also being advised to look at coverage gaps as well as price, as one Newfoundland town did when it added pollution coverage to its municipal policy. Bids that compare fees directly and explain the risk management service behind them are likely to have an advantage.