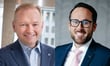
New capacity keeps pouring into Canada’s commercial insurance market, and domestic insurers are now competing for business once contested mainly by global carriers, according to Bernard McNulty (pictured left), chief agent, Canada, at Allianz Commercial.
“The influx of new capacity coming into Canada, not just in direct markets, but in MGAs too, is bringing increased competition but also creating opportunities for us to demonstrate our value, deepen client relationships and identify new avenues for growth,” McNulty told Insurance Business.
Read more: Allianz Q3 cat bill jumped 17-fold as group profit hit a record
That has made the insurer fight harder to keep its portions of accounts, he said.
Allianz has typically competed only with other global insurers, he said, but some domestic carriers, such as Wawanesa, are now moving into its space.
“More recently we’ve seen a little more competition from domestics,” McNulty said.
The answer is to stay close to clients and excel at the work, he said, adding that “we have to service our clients and look after them.”
Shanil Williams (pictured right), president, Americas, and CEO, North America, at Allianz Commercial, said the insurer’s approach in a softening market is what it calls “smart growth,” with the bottom line as the main focus for stakeholders.
Allianz aims to be the most trusted partner for large, multi-year clients with sophisticated risk managers, Williams said. Those relationships may be less profitable in a given year, he said, but they pay off over the full cycle.
Even when the market softens overall, many subsegments remain rate adequate, and Allianz uses its technical expertise to find them, Williams said.
“One of the big levers is business mix,” he said.
A very soft property market can be balanced with lines that haven’t softened as much, Williams said. He added that Allianz makes sure its underwriters “aren’t just growing for the sake of it, but growing for the right relationship, the right broker, and the right signals.”
Multinational business remains a major opportunity in Canada, McNulty said. With trade tensions with the U.S., many Canadian companies are diversifying their sales and service into Europe and elsewhere, and turning to Allianz to issue local policies in the more than 200 countries it can service.
“Multinational is a fantastic opportunity for us right now,” he said.
Allianz is still focused on helping clients prevent losses within large retentions, McNulty said, and is now bringing in more global specialists, such as nuclear and tunnelling experts, to work on Canadian projects. That support extends across sectors, from highly sophisticated risks to manufacturing and real estate.
“I would say we’ve just expanded the expertise that we bring to the table for Canadian clients,” he said.
On data, McNulty said the industry is at different stages. Allianz spends a great deal of time and money on data quality and how it uses data, he said.
“I’d like to think we’re further ahead than some,” McNulty said.
McNulty said this year has been quiet for catastrophe losses among Allianz’s commercial clients in Canada, with only one wildfire claim.
That claim came from a client with more than 300 locations, he said. The damage at any single site was limited, but because each location carried some exposure, the losses added up to a sizable claim. For clients with large portfolios of properties, McNulty said, that means wildfire losses tend to be infrequent but significant when they do happen. The challenge for the insurer is to understand every asset a client has and where each one sits.
Even so, Allianz isn’t changing how it underwrites wildfire, McNulty said. In Canada, personal lines and SME and mid-market insurers take the bulk of wildfire claims.
Williams said AI’s main value lies in making Allianz faster and more nimble for customers.
“Our industry in general is document heavy, rules heavy, data heavy,” he said. “If AI can make us more productive on a lot of the menial tasks there, then we think that can turn into better service, better retention, potentially better innovation.”
AI could also cut the frictional costs in how commercial insurers trade with brokers by bringing more standardization to the marketplace, Williams said.
On the risk side, insurers hold sensitive data that must be protected, he said, and Allianz is “very conscious of our cyber resilience as AI comes in.” Clients are also increasingly delivering services and running manufacturing operations through AI, which creates new risks that insurers need to understand and price, Williams said.
Looking ahead to 2027, Williams said forces outside the industry will matter most, from natural catastrophes and climate change to trade, tariffs and war.
“Insurance drives and underpins the economy,” he said.
Read more: AI wants to please you, and that’s a problem for claims, Allianz exec warns
How insurers respond will be just as important, Williams said, including whether they have the resilience to underwrite new risks and pay claims appropriately. He said the industry has invested heavily over the past decade in better pricing and predictive tools, which should help reduce “blind underwriting” and bring more stability. Still, conditions differ sharply across lines: in the U.S., liability is harder while property is softer, creating more “cycles within a cycle.”
“I think there’s so much complexity in the type of risks that it’s very hard to give any set projection,” Williams said.