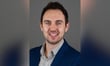
Life insurers are testing artificial intelligence across underwriting, pricing, product development and operations, but the industry hasn't yet built the governance frameworks needed to deploy it responsibly, according to Matthew Berman (pictured), president and CEO of Foresters Financial. The bigger question, he said, isn't how fast the sector is moving. It's whether insurers are building the discipline to question what the technology tells them.
"The playbook is currently being written," Berman said.
Data-driven underwriting isn't new, Berman said. Insurers have relied on electronic health records, driving histories and third-party databases for years to price products and predict outcomes. What's changed is that generative AI has made the public aware of processes the industry has used for some time, reshaping what customers expect to be told.
"AI as a technology has captured so much mindshare over the past couple of years that it is now putting a spotlight on processes and areas that the industry has used for quite some time," Berman said.
Read more: AI job elimination fears are 'a bit of a myth,' Deloitte's Sood says
That shift comes with an obligation, he said, both to customers and internally.
"I do think we have a duty to share how we either arrive at decisions or how we arrive at outcomes and how we are using technology today," Berman said. "I think we have a duty to make sure that we are appropriately stress testing the outcomes that these models can drive."
Asked whether insurers are moving too cautiously or not cautiously enough on AI, Berman said that framing misses the real risk.
"Life insurers are risk-managing institutions by design. Many have been around for more than a century. There's a reason for that," Berman said.
That caution isn't unique to any one company, Berman said. The sector manages enormous volumes of information, decades-old blocks of business and legacy systems, all within a heavily regulated environment, and new technology has to be introduced and tested with those realities in mind. His sense is that insurers, broadly, are moving about as quickly as they responsibly can.
That approach is already taking shape at Foresters. Berman said the company is using AI to interpret multiple data sources more intelligently within its underwriting process, with the goal of improving speed and efficiency while keeping human judgment at the centre of decision-making. The work is moving beyond the pilot stage, with the capability expected to enter production next month.
"The technology is becoming easier to use every day. For organizations like ours, the responsibility that comes with using it is becoming more complex," Berman said.
The bigger danger, he said, is what he calls "cognitive surrender": accepting an AI-generated answer simply because the technology produced it. AI can hallucinate or produce an answer that sounds credible but isn't, a problem that carries real consequences once it touches underwriting, pricing, claims or policyholder information.
"You can move cautiously and still get it wrong. What matters is whether you can stand behind the decisions the technology helps you make," Berman said.
For an industry handling claims that affect families and beneficiaries directly, Berman said, the tolerance for mistakes is thin.
"The margin for error is so small – if you misstep on a claim that's impacting families, beneficiaries, that broken trust is so difficult to repair," Berman said. "There is incredible opportunity, but there is existential risk. It takes one incident to capture a headline. And if there is proven systemic negligence, it can have disastrous outcomes."
The answer, he said, isn't to pull back but to build governance that keeps humans accountable for consequential decisions on underwriting, claims and pricing.
"Operating in a vacuum and not disclosing or building good governance – those are surefire ways to misstep," Berman said.
Read more: Access to AI is not the same as being ready for it
On the sales side, Berman doesn't expect AI to replace advisors, particularly for complex products, even as it speeds up prospecting and underwriting support industry-wide.
"I'm a big believer that a human in the loop, an advisor, is paramount to the sale," Berman said.
Done responsibly, Berman argued, AI could also change who life insurance actually reaches. The industry has historically skewed toward wealthier customers who can afford premiums and navigate the complexity of buying a policy, a pattern he said faster, cheaper operations could help reverse.
"Life insurance typically has been a solution that has over-indexed to affluent families," Berman said. "If we can get this right and we can build more scale, drive efficiency, land better pricing, democratize the industry – I think that is an incredible milestone for our sector."