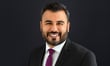
The hospitality sector shows how difficult it can be for insurers to stay with a market when conditions turn, said Jatinder Bassi (pictured), president of Echelon Insurance.
“We do see some insurers that come in and come out of certain market segments,” Bassi said.
He described that behaviour as insurers looking to “jump on something when there’s an advantage and then pull out when they start seeing red or orange or yellow.”
Read more: Canadian insurance market faces another soft year, but warning signs are emerging
During the pandemic, many insurers pulled out of hospitality because of uncertainty, Bassi said. Echelon was already writing the sector at the time and provided additional support to it after seeing that businesses still needed coverage, he added.
“We’re starting to see pressure in some markets as standard insurers return to lines of business they have stayed out of for the past four or five years, recognizing that market conditions have changed,” he said.
Those markets are returning with no recent loss history in the sector, Bassi said.
“The reason for pulling out didn’t make sense either,” he said.
Cyber has faced a similar problem, he said, though Bassi added that he could not speak for how other insurers decide when to enter or exit a line.
Remaining in a line of business through a loss year is difficult to justify, particularly in a soft market, Bassi acknowledged when asked how an insurer makes that business case.
“Absolutely. It’s not easy,” he said.
Rather than moving in and out of lines, he said, Echelon’s growth plans focus on specializing further within segments it already writes. In commercial auto, that includes logging, forestry and municipal risks. In commercial property, it includes manufacturing, data centres, medical developments and long-term care facilities.
“We’ll continue to focus on where we see the economy heading and how we can specialize in those areas,” he said.
Returning markets add to the capital already competing for business, Bassi said. Insurers have taken on more of their own losses through higher retentions, while capacity continues to grow and certain pockets of the market are softening.
Not every line is easing, he said.
“I would say property is fairly stable, maybe slightly on the harder side,” Bassi said.
Catastrophe losses have been relatively low across Canada this year, but they have been concentrated in certain areas, he said, which has kept insurers cautious.
“I think that’s the reason why the industry hasn’t been complacent, because there are certain areas that are still being impacted by weather change,” Bassi said.
Even so, the growing supply of capital raises a question about how far pricing can fall, he said.
“At what point do we say the pricing no longer makes sense?” he said.
When a market looks appealing, Bassi said, one of the most useful signals comes from insureds’ own spending on risk control. Echelon’s technical risk services team tracks how much clients invest in maintaining their risk posture, he said, and brokers provide a second line of sight because they are in direct contact with insureds.
“If insureds start to deprioritize maintaining structures, maintaining their processes to manage their risks, and they start cutting back on individuals or programs, that’s a key indicator that the risk is no longer the same risk it was previously,” Bassi said.
He said businesses facing economic challenges tend to look at risk control early when searching for savings, which effectively shifts that cost onto their insurers.
“That’s one of the cost areas that is not a revenue generator,” Bassi said.
Interest rates are a second indicator he watches, along with the pressure they place on consumer spending and on businesses’ ability to service debt. Frequency and severity trends, and the effect of inflation on loss costs, round out the metrics Bassi said he follows.
Insurers are also dividing risks into ever narrower pricing groups, Bassi said, which has a cost for the most exposed businesses.
“As we continue to enhance segmentation strategies across the industry, you end up with a market that’s segmented out of the insurability area,” he said.
Bassi said brokers have a duty of care to clients heading into 2027 renewals, and that the choice of insurer is part of it.
“Obviously, price is one of those factors, but it can’t be the only factor,” he said.
Renewals are an opportunity to check that clients carry adequate limits, appropriate deductibles and the right coverage, and to consider whether the product offering can be improved, Bassi said. Brokers should also look at how smoothly an insurer handles the claims process, he said.
Read more: Businesses underestimate how long a loss can keep them down, Echelon exec says
Bassi described the relationship between broker and insurer as a bigger factor than price, because brokers hold the information an insurer needs to provide sufficient coverage. Clients, he said, are asking the same questions.
“Do I have enough insurance? Do I have enough coverage? Was I given the right product? And are those risks still insurable?” he said.