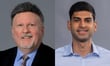
Artificial intelligence could leave insurers with weaker pricing models exposed to adverse selection, as competitors use more granular data to pick off their best business, according to Alan Murray (pictured left), director at AM Best.
“I think AI will bring in a level of greater granularity of risk pricing,” Murray told Insurance Business.
He said insurers that try to keep prices level across a portfolio are most at risk.
Read more: Canada’s P&C industry can absorb another 2024-scale cat year, AM Best says
Murray said insurers with more accurate risk models can gain a competitive advantage by offering lower prices on risks they believe competitors have overpriced, attracting their better business. This leaves competitors with a less favourable portfolio, having lost some of their appropriately priced risks while retaining more policies that are underpriced for the risk they carry.
Murray said insurers that prioritize stable pricing over precise risk matching become vulnerable over time.
“If you’re an insurer that looks more for stabilizing prices, you run the risk of not matching risk with price,” he said. “You run the risk over time of getting cleaned out of your profitable business.”
Most insurers already sort policyholders into performance tiers, he said, then fix or drop underperforming accounts. But “not all insurers are equally disciplined in that across all their businesses,” Murray said.
He said AI could also sharpen fraud detection, finding patterns across claim types, locations, the number of people involved, and networks of dealers, lawyers and medical providers that a person reviewing one database at a time could miss.
“In theory, this stuff has been a focus of insurers for a long time. It’s just they have a new gadget to turn up, dial up the speed,” Murray said.
Technology alone isn’t enough, he said.
“The technology and the speed to analyze things is quicker, but you have to have the management to decide how to use it and how to act upon it,” Murray said.
Ravi Mittal (pictured right), financial analyst at AM Best, said AI is already improving underwriting, claims handling, fraud detection and catastrophe risk management, based on what insurers show AM Best in management meetings.
“We already see in underwriting and claims handling, we see technology being used a lot and adopted a lot and improving things and streamlining processes,” Mittal said.
The broader financial payoff has yet to arrive, Mittal said.
“A lot of insurance companies are still premature in their AI usage, very early stages. It’s not transforming their results or anything like that,” Mittal said.
Mittal said the growing use of AI is introducing cyber threats that the insurance industry may not be adequately prepared to address, particularly as attacks become more sophisticated and capable of affecting multiple organizations simultaneously.
“One big thing that we see is cyber risk as a risk that’s not talked about quite enough with AI coming into place,” Mittal said. “We see AI incidents; we see ransomware attacks as well, systemic events that affect multiple companies at the same time.”
He questioned whether conventional risk-modelling methods and cybersecurity measures can keep pace with attacks enabled by AI. With cyber risk among AM Best’s key areas of concern for 2027, the impact of potential attacks on insurers will be an important issue to watch, he said.
Mittal said insurers have yet to see AI significantly replace employees, partly because the sector has been slower to modernize than industries such as technology.
“I’ve asked companies if AI is replacing employees in your company, and they’ve said not at all,” Mittal said. “For me personally, I don’t see it replacing employees as of right now.”
Read more: Brokers should stop asking clients if they use AI and start asking how, CFC exec says
Murray cautioned that the industry's slower adoption of technology could leave it vulnerable to disruption, even if the effects on employment remain uncertain. While some technology companies in California have made substantial workforce cuts, he noted that their business models are more directly tied to technology than those of most insurers.
The insurance industry has automated processes for decades, Murray said, and further advances in automation and analytics are likely to change how some roles are performed.
“Certain people’s jobs will need to be retooled. That goes without question,” Murray said.