Managing general agents aren't just changing how insurance gets distributed in Canada, they're changing who ends up holding the risk behind it, according to a panel of industry executives speaking at a recent conference. Two structures in particular, captive insurance and fronting arrangements, are pulling capital into the market in ways that look increasingly similar to what's already playing out in the US.
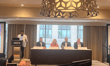
Captive insurance, where a company essentially insures its own risk through a structure it owns, is seeing renewed growth in Canada, according to Paul Jackson (pictured centre right), CEO of Zurich Canada. Large businesses are increasingly using captives to rethink how they allocate capital, he said, and Zurich is investing in that capability both globally and domestically.
Read more: MGAs write a third of UK commercial lines. In Canada, they're not even in the textbooks
"In Canada, we're seeing a real surge in growth of captives as large businesses look to allocate capital differently and think about risk differently," Jackson said.
Jackson was careful to draw a distinction between captives and MGAs, even though both involve a company taking on more direct control over its own risk. Captives serve large, single insureds looking for an efficient way to hold their own frequency-level losses, he said, while MGAs are fundamentally about distribution, not capital retention.
"On the MGA side, we see that a little differently. That's more about access to distribution," Jackson said.
Matt Wolfe (pictured right), president and CEO of Aon Reinsurance Solutions Canada, said captives tend to become more attractive whenever the reinsurance market hardens and that pressure flows through to primary insurance pricing. A large, well-capitalized company eventually reaches a point where standard deductibles stop making financial sense on their own.
"A $250,000 deductible doesn't make any sense for a multi-billion-dollar company," Wolfe said, adding that captives let a business absorb its own smaller, more predictable losses directly while still turning to the external market for the risk it can't reasonably carry itself.
That same logic, Wolfe said, is starting to extend to MGAs as well, particularly the larger, broker-owned operations with the financial resources to build a captive of their own and take on a direct underwriting stake alongside their carrier partners.
Where captives let a company hold more of its own risk, fronting works in the opposite direction, bringing in capital that has no direct relationship with the insured at all. In a fronting arrangement, a licensed insurer issues the policy on paper while a separate party, often an MGA, a captive, or the reinsurance market itself, actually carries the risk behind it.
Wolfe traced the model's roots in the US back decades, built originally around specialty MGAs with long-standing relationships with major reinsurers. Those reinsurers were often willing to take on 100% of an MGA's risk but lacked the licensed paper needed to issue policies directly, creating an opening for fronting carriers to step in.
"They basically come out and say to the MGA: ‘Okay, we will charge you a certain amount of fee, we'll require a certain amount of collateral, and provided that you get high-quality reinsurers that we know and rely on, we'll give you our paper and then we can reinsure 100%’," Wolfe said, citing US fronting specialists like State National, part of the Markel Group, as examples of that model in practice.
Read more: Alternative capital wants closer access to MGA risk, Aon exec says
What's changed more recently, according to Wolfe, is the type of capital now backing those arrangements. Alternative capacity, money from pension funds, hedge funds, and other asset managers, is increasingly stepping into the same role reinsurers once played alone.
"You already have carriers in Canada that will deploy their paper. I think often they take maybe a very modest line, and then it'll be largely reinsured," Wolfe said. Canada hasn't seen anywhere near the volume of fully reinsured fronting deals that the US market has, he said, but he expects that gap to close over time as the fronting model migrates north.
Wolfe was direct about the central danger in the fronting model: a carrier that fronts a policy doesn't get to walk away from it just because it intended to pass the risk along entirely.
"You have to really understand counterparty credit risk. You have to understand reinsurance contracts, because ultimately the carrier cannot say, well, I was just fronting this policy," Wolfe said. "If it is your name on that insurance company policy, the insurance company is on the hook."
That risk isn't limited to whether a reinsurer can ultimately pay, according to Sridhar Manyem (pictured left), senior director at AM Best, who noted that recent market disruptions have shown the need to scrutinize the collateral backing a reinsurance arrangement just as closely as the reinsurer itself, including instruments like letters of credit that are meant to guarantee that capital is actually there when a claim comes due.
Taken together, both trends point toward the same underlying shift: as Canada's MGA market matures, the capital standing behind it is diversifying well beyond the traditional insurer-reinsurer relationship, and the parties relying on that capital are having to get considerably more rigorous about verifying it's actually there.