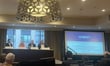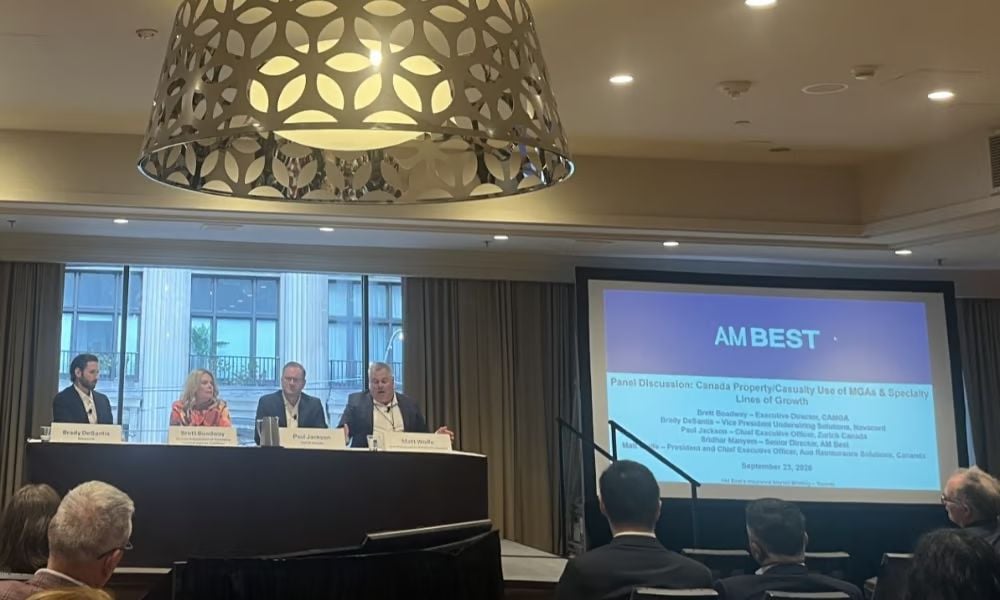
The managing general agent segment is one of the fastest-growing corners of Canada's insurance industry, according to Brett Boadway (pictured centre left), executive director of the Canadian Association of Managing General Agents, speaking on a panel at a recent industry conference. But several things haven't kept pace with that growth: reliable data on how big the market actually is, any meaningful effort to bring new talent into it, and, according to some of the insurers who work with MGAs directly, a clear enough standard for what actually makes one trustworthy.
"Canada has not done a great job of actively tracking this data, which presents an amazing opportunity for the trade association to take on that responsibility," Boadway said, describing how CAMGA meets quarterly with its counterparts in the UK, US, Australia, New Zealand and Europe, several of which have built far more robust tracking systems for their own delegated authority markets.
Without that infrastructure in place yet, Boadway said, CAMGA is working from estimates rather than hard data, though the association is building its own model based on work already done by peer associations abroad.
Read more: Alternative capital wants closer access to MGA risk, Aon exec says
"We estimate that there are 100 to 120 MGA firms across Canada, which is different than brands, because sometimes within each firm they have multiple brands," Boadway said. Those firms write an estimated $4 billion in gross written premium, she said, representing roughly 10 to 15% of all commercial lines business in the country.
That share is still well behind more mature markets, according to Boadway, but the trajectory points in one direction.
"The MGA market is growing, not slowing, and we project that we're on the trajectory to follow our counterparts in other countries," Boadway said. "In the UK, MGAs now write one-third of all commercial lines business." She added that roughly half of Lloyd's corporate premium already flows through MGAs, a figure well beyond where Canada currently sits.
That growth hasn't translated into awareness, according to Matt Wolfe (pictured right), president and CEO of Aon Reinsurance Solutions Canada, who said the problem starts with how the industry presents itself to newcomers long before they ever encounter an MGA directly.
"I often bemoan that we as an industry don't do a great job of marketing ourselves to young people as an exciting, dynamic industry," Wolfe said. The reality, he said, is closer to the opposite: insurance touches nearly every interest a young person could have, whether that's fine art, classic cars, or something else entirely niche, and MGAs in particular tend to be built around exactly those kinds of specialized passions.
Boadway took that point further, describing a small, informal test she ran herself.
"I spent some time this summer looking through all of the textbooks of some foundational learning courses in the industry… Do you know how often MGAs are listed in these foundational textbooks? Not once,” she said.
Wolfe said the entrepreneurial appeal that has historically attracted ambitious young people to smaller brokerages is now showing up in MGAs as well, particularly for underwriters with deep, specialized knowledge.
"If you're a really driven, ambitious young person and you want to join a smaller, mid-sized brokerage, you have an opportunity, potentially, to have a share of the financial success that you bring to your firm," Wolfe said. "I think the MGA market should really try to be showing these people that there's significant opportunity in the MGA space."
That opportunity comes with a catch, according to Paul Jackson (pictured centre right), CEO of Zurich Canada, who said the profile of talent MGAs need has shifted as the market has matured. A deep specialty in one narrow area, once sufficient on its own, isn't enough anymore.
Read more: CAMGA wants a national MGA standard. Zurich's CEO says fine, but don't stop there
"As MGAs have become more general, larger, and more prominent in the market, we're looking also for technical insurance knowledge and expertise as well," Jackson said. "I also want you to have the capability to think and act like an insurer. As the market grows, I think the talent profile needs to evolve as well."
Brady DeSantis (pictured left), vice president of underwriting solutions at Navacord, pointed to technology as one lever MGAs can use to attract the kind of underwriting talent that might otherwise stay locked inside a large global carrier.
DeSantis pointed to large master binding facilities as one option, where an underwriter could take on a specific book of business under that broader agreement rather than needing to build an entire standalone MGA from scratch.
That model is already established in the US, he said, and making that transition easier for an underwriter with 10 or 15 years of experience at a large firm is something MGAs will increasingly need to build toward if they want to capture that talent rather than compete against it.
Growing the talent pool is only half the equation, according to Wolfe and Jackson: an insurer still has to decide which MGAs it's willing to trust with delegated authority in the first place, and that judgment starts long before any contract gets signed.
For Wolfe, it comes down to a long-term mindset over short-term volume. The MGAs that last, he said, are the ones built around sustainable underwriting discipline rather than chasing premium for its own sake.
"It’s very easy to go and chase premium if you're an MGA, generate significant commission income, and then have very poor underwriting results," Wolfe said. "The MGAs that continue to grow, the MGAs that continue to add capabilities, the MGAs that continue to be able to invest in technology and people are the ones that are fundamentally committed to an underwriting mindset."
Read more: The US border is doing more work than people assume in Canadian insurance
Jackson described evaluating MGAs through what he called two lenses: character and capability, weighed together rather than separately. The character read, he said, often happens within the first few minutes of a meeting.
He said those first impressions form almost immediately: who the people across the table are, where they've come from, and how they carry themselves in the room. He described sitting through meetings where, half an hour in, he still had no clear sense of what the MGA actually did or how it operated, calling that itself a warning sign. A well-prepared MGA, by contrast, tends to stand out right away.
"People come in sharp, equipped, well-rehearsed, well-presented, put some materials on the table, structure a conversation. Now you have my attention," Jackson said.
That first impression, Jackson said, is only where the evaluation starts. From there, Zurich digs into harder evidence: a track record of performance, technical capability, and above all, how reliable and consistent an MGA's data actually is, since that consistency is what sustains trust as the relationship is monitored over time.
"I look at it two ways," Jackson said. "It's about people and character as much as it's about hard skills and capabilities."