Canada recorded CA$8.5 billion in insured catastrophic losses in 2024 – the highest annual total in the country’s history, according to the Insurance Bureau of Canada (IBC). That figure is nearly triple the insured catastrophe total from 2023 and 12 times the annual average of CA$701 million recorded between 2001 and 2010.
For property and casualty (P&C) insurers, brokers, and their clients, the numbers represent more than a claims spike. They signal a structural shift in how risk is modelled, priced, and distributed across the Canadian market.
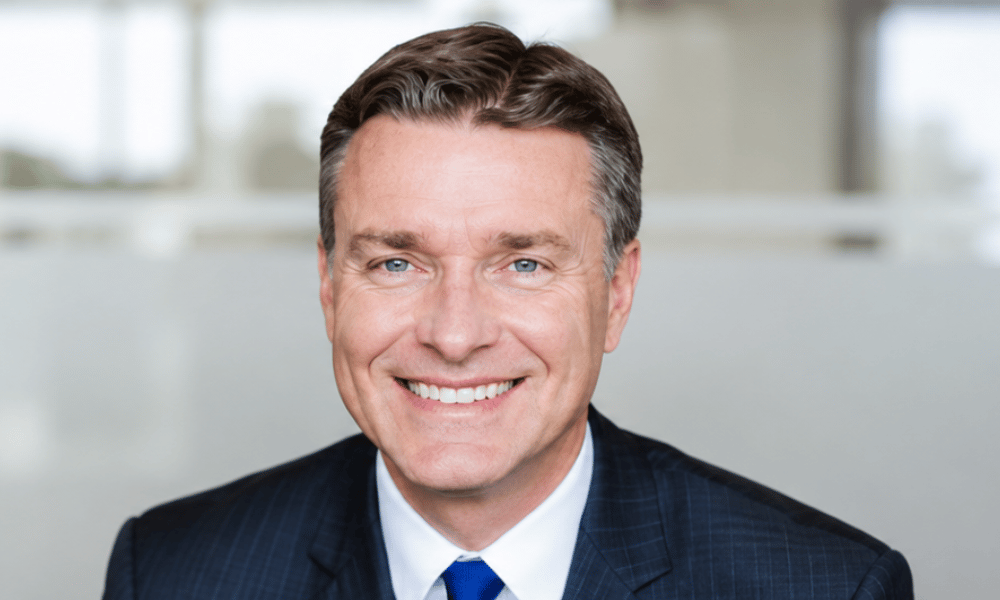
Paul MacDonald (pictured), executive vice-president, personal insurance & digital channels at Definity Financial Corporation in Waterloo, Ontario, says the industry’s response begins with underwriting discipline – not retreat.
Read more: Canada’s home insurance market tightens as climate losses bite
“Extreme weather events are no longer anomalies in Canada – they have become recurring operational realities that demand modern risk modelling and highly disciplined underwriting,” MacDonald said.
His argument hinges on market structure. Where some international markets have seen carriers pull back from high-risk regions, Canada’s competitive depth spreads exposure across a wide field of insurers.
“A diverse and competitive market allows multiple carriers to take varying portions of climate risk, ensuring that capacity remains distributed and resilient,” he said.
Definity’s approach has been to use advanced analytics to stabilise its underwriting position while keeping capacity available through a multi-market model.
For properties in overland flood zones or wildland-urban interfaces, MacDonald does not describe a narrowing of appetite. He frames broker access as the mechanism keeping coverage reachable, even as risk profiles become more complex.
“Brokers play an essential role here. They leverage their access to a wide array of competing carriers to distribute risk effectively, ensuring homeowners and commercial clients find adequate protection,” he said.
Definity’s approach has been to give brokers transparent risk data, flexible tools, and product variety rather than reduced appetite. In 2025, the company trained more than 800 broker partners through its Protecting Clients Against Floods and Wildfires course, according to Definity’s 2025 Sustainability Report.
MacDonald says Definity’s focus has shifted toward loss prevention before an event rather than claims management after one. The company promotes backflow valves, sump pumps, improved drainage systems, and wildfire-resistant building practices, and offers coverage options that support resilience upgrades post-loss.
Consumer demand for this role is measurable. The Definity 2026 Climate Resilience and Adaptation national survey – which polled 1,500 Canadian auto and home insurance shoppers in March 2026 – found that 81% expect their insurer to actively help them reduce risk and prevent losses. More than half said they would switch to a provider committed to sustainability and transparency, according to the same survey.
Read more: From Jasper fires to Hurricane Debby: climate shocks reshape Canada’s P&C market
The IBC has been direct about what sustained loss escalation means for the broader market. Following a federal audit of Canada’s National Adaptation Strategy in June 2025, Craig Stewart, vice-president, climate change and federal issues at the IBC, said: “The federal government has underperformed on commitments to protect Canadians from the wildfires, floods, windstorms and hailstorms affecting hundreds of thousands of Canadians today.”
Stewart noted that over the past decade, federal spending on climate mitigation – measures that reduce emissions over 20 years to 30 years – was 10 times greater than spending on adaptation measures that address the risks Canadians face now. That funding imbalance, the IBC argued, must be reversed.
MacDonald’s position aligns with that assessment. Definity holds a leadership role in Climate Proof Canada (CPC), a national cross-sector coalition that includes the IBC, the Insurance Brokers’ Association of Canada (IBAC), Intact Financial Corporation, Aviva, Co-operators, Desjardins, Gore Mutual, Wawanesa, and Zurich Canada, among others.
“Maintaining affordable and accessible insurance will require a whole-of-society approach, with insurers, governments, businesses and homeowners all playing a role. Continued investment in resilient infrastructure, stronger building codes, climate-informed land-use planning, and flood and wildfire mitigation measures, including the protection of natural infrastructure, will be critical to reducing future losses and helping close Canada’s protection gap over the long term,” MacDonald said.